Helping Yuba, Butte, and Nevada County Homeowners Find High Fire Coverage
Oakview Insurance Services, Inc. is an independent insurance agency headquartered in Yuba City, CA. Since 2010 we’ve helped homeowners, landlords, and property owners across Yuba, Butte, and Nevada Counties find coverage after their carrier restricted it or declined to renew. We have 19 licensed advisors on staff and 850+ five-star Google reviews.
If no standard carrier will write your address anymore, California has a last-resort fire program for eligible properties the normal insurance market won’t take. We shop standard and surplus lines carriers first. When those options run out or cost too much, we help you apply to the last-resort program and set up a companion policy for what it leaves out. Our recommendation comes from looking at your property, your location, and your budget.
What Is Last-Resort Fire Coverage in California?
The program’s official name is the California FAIR Plan (Fair Access to Insurance Requirements). State law created it in 1968 to provide basic property insurance for eligible homes and businesses that can’t get coverage in the normal insurance market, which includes both admitted carriers and surplus lines insurers. It writes in urban and rural areas and is overseen by the California Department of Insurance. Eligibility, limits, and policy options follow the program’s current rules.
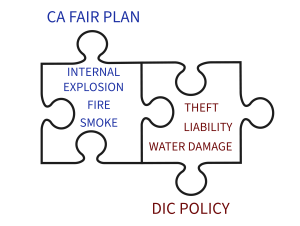
A last-resort policy covers far less than a homeowners policy. The basic policy is named-peril and covers fire, lightning, internal explosion, and smoke. Extended coverage perils and vandalism or malicious mischief can be added for an extra premium. Theft, water damage, and personal liability aren’t covered, which is why we recommend looking at a Difference in Conditions (DIC) policy any time last-resort coverage is on the table. The two together can work much like a traditional homeowners policy, though the limits, deductibles, exclusions, and conditions won’t match a single standard policy.
The program keeps changing as wildfire losses put pressure on the California market. Limits, payment plans, and the wildfire hardening discounts have all been revised in the last few years, and we track those changes for our clients.
Why Work With a Local Independent Agent
The application has requirements that trip up homeowners who try it alone. A licensed local agent knows what the program will ask for and gets the paperwork right the first time.
Expect to provide accurate property details, photos of the home, and sometimes other documents. We tell you exactly what to gather before you start. In our recent experience, a complete application is usually approved within 48 to 72 hours, and many come back in 24 hours or less. Missing photos or paperwork are what slow things down. You can pay in full or in installments, and we go over what’s due before we submit. Coverage starts only once the program confirms it.
We line up the companion DIC policy so the effective dates match, then compare the two policies side by side to find any gaps left over. Your address, fire protection class, construction, and defensible space all shape what’s available, and we know how to present your property to underwriters.
As an independent broker with access to 100+ carriers (including Orion 180, Green Shield, SageSure, Aegis, Delos, Solara to name a few), we check the standard market first. If a carrier is still writing in your area, we’ll find it. The last-resort program comes in only after the standard market has closed to you.
County-Specific High Fire Insurance Resources
Carrier appetite, fire hazard severity zones, and local market conditions differ a lot between Yuba, Butte, and Nevada Counties, so each county has its own guide.
Yuba County High Fire Insurance
For Dobbins, Oregon House, Loma Rica, Browns Valley, Smartsville, and surrounding communities in eastern Yuba County. These foothill communities sit in or near CAL FIRE Fire Hazard Severity Zones, and many standard carriers limit or decline new business there.
Yuba County High Fire Insurance Guide
Butte County High Fire Insurance
For Chico, Paradise, Oroville, Magalia, Concow, and surrounding communities. Butte County’s market took hits from the 2018 Camp Fire and the 2024 Park Fire, which burned 429,603 acres and ranks as the fourth-largest wildfire in California history according to CAL FIRE. Many homeowners there have watched their standard options shrink since.
Butte County High Fire Insurance Guide
Nevada County High Fire Insurance
For Grass Valley, Nevada City, Penn Valley, Truckee, and surrounding communities. Exposure data published by the last-resort program in 2024 listed Nevada City, Grass Valley, and Truckee among the areas with the highest wildfire exposure concentration in California. Some Nevada County properties can still get standard coverage, and we check every one of those carriers before recommending the last-resort route.
Named-Peril Fire Policy and DIC Coverage Breakdown
A last-resort fire policy is named-peril, so it pays only for the causes of loss listed in the policy. The basic policy covers fire or lightning, internal explosion, and smoke. Extended coverage perils (windstorm, hail, explosion, riot, aircraft, vehicles, and volcanic eruption) and vandalism or malicious mischief are optional and cost extra.
Theft, water damage, and personal liability are left out. A Difference in Conditions (DIC) policy is built to pick up those gaps. Depending on the insurer and policy form, it may cover theft, certain water damage, personal liability, and loss of use. We set up both policies and read them together, so you know what each one covers and where anything is still missing.
Major Wildfires That Changed Northern California’s Insurance Market
Northern California’s insurance squeeze built up over several fire seasons. Each major fire changed how carriers price and underwrite wildfire risk, and more homeowners have landed on the California FAIR Plan as a result.
- Camp Fire (2018): The deadliest and most destructive wildfire in California history. It destroyed Paradise and the surrounding Butte County communities, killed 85 people, and leveled more than 18,000 structures. For homeowners insurance in this region, it was the turning point.
- North Complex Fire (2020): The Bear Fire, part of the North Complex, tore through Berry Creek in Butte County. The complex burned more than 318,000 acres across Butte, Plumas, and Yuba Counties, and carriers pulled back further from foothill and forested communities in the months that followed.
- Dixie Fire (2021): Burned 963,309 acres across Butte, Plumas, Lassen, Shasta, and Tehama Counties. It destroyed Greenville, damaged communities around Lake Almanor, became the first fire on record to burn across the crest of the Sierra Nevada, and is still the largest single-ignition wildfire in California history.
- Caldor Fire (2021): Destroyed Grizzly Flats and pushed toward South Lake Tahoe, forcing the city’s evacuation. Days after the Dixie Fire, it became only the second fire on record to burn across the Sierra crest. Underwriting tightened across El Dorado County and the surrounding Sierra foothills afterward.
- Park Fire (2024): Burned 429,603 acres across Butte, Tehama, Plumas, and Shasta Counties, making it the fourth-largest wildfire in California history. It added pressure to an already tight insurance market in Butte County and the surrounding area.
An analysis of California Department of Insurance data found that in 2023, insurers non-renewed more homeowners policies than they wrote new ones in 46 of California’s 58 counties. If you live in Yuba, Butte, Nevada, Sutter, or Colusa County, that’s why your renewal notice looks different than it did five years ago.
Wildfire Hardening Discounts
California’s last-resort fire program offers discounts for qualifying improvements to your home, the area right around it, and certain recognized community mitigation projects. A Class A fire-rated roof, ember-resistant vents, upgraded windows, and documented defensible space can lower the wildfire portion of your premium, and standard carriers look at the same improvements. The program’s statewide average rate increase of 29.1% took effect for new and renewal policies on October 15, 2026, so the discounts are worth chasing. How much your own premium changes depends on your property and policy. We’ll go over what qualifies and how to document the work.
Learn More About Wildfire Hardening Discounts | 2026 Rate Increase: What Homeowners Should Know
What Our Clients Are Saying
Oakview Insurance Services has earned 850+ five-star Google reviews from clients across Northern California. High fire clients often mention that we checked every standard option first, explained the DIC process in plain terms, and got their policies in place without surprises.
Read what our clients say on Google or meet our team to learn more about the advisors behind the agency.
Frequently Asked Questions: High Fire Insurance in Northern California
What does last-resort fire coverage include?
The basic last-resort policy is named-peril and covers fire, lightning, internal explosion, and smoke. Windstorm, hail, and other extended coverage perils, plus vandalism or malicious mischief, can be added for an extra premium. Theft, water damage, and personal liability aren’t covered. A Difference in Conditions policy may be needed for those, and we set up both policies and review them together.
Is last-resort fire coverage the same as the California FAIR Plan?
Yes. Last-resort fire coverage and the California FAIR Plan are the same state-mandated program. We use both names because homeowners search for both. Oakview is an independent broker. We represent you, not the California FAIR Plan, and the program decides eligibility, policy issuance, and terms.
What is a Difference in Conditions policy and do I need one?
A Difference in Conditions (DIC) policy is a separate policy built to pick up gaps in a last-resort fire policy. Depending on the insurer and policy form, it may cover theft, certain water damage, personal liability, and loss of use. We recommend looking at one any time last-resort coverage is needed, and we review both policies together so you know the exclusions, limits, deductibles, and any gaps that remain.
Is last-resort fire coverage my only option if I received a non-renewal notice?
Not necessarily. We check admitted and surplus lines carriers through our 100+ carrier relationships before recommending last-resort placement. Surplus lines insurers have more room to underwrite than admitted carriers and may write a home an admitted carrier declined. If the normal market can’t cover your home at a workable price, the last-resort program may be an option for eligible properties.
How long does it take to get a last-resort fire policy bound?
In our recent experience, a complete application is usually approved within 48 to 72 hours, and many come back in 24 hours or less. Missing photos or documents cause most delays. We help you gather everything up front, go over the payment options, and coordinate your effective date. Coverage starts only once the program confirms it.
Can I get a discount by hardening my home against wildfire?
Yes. California’s last-resort fire program offers discounts for qualifying improvements like a Class A fire-rated roof, ember-resistant vents, upgraded windows, and documented defensible space. The discounts apply to the wildfire portion of the premium, and the amount depends on which criteria your home meets. We’ll go over what qualifies and how to document your improvements.
How do I get a quote for Yuba, Butte, or Nevada County?
Call (530) 674-5054 or fill out our online quote form. We’ll ask about your property’s location, construction, fire protection class, and any hardening work you’ve done. Then we check standard and surplus lines carriers before bringing up last-resort options. You’ll hear back quickly, with straight answers and no sales pressure.
Ready to Get Started?
If you’ve received a non-renewal notice, can’t find coverage, or just want to know where you stand, call us or start a quote online. We’ll look at your property and give you straight answers about your options.
Phone: (530) 674-5054
Email: info@oakviewins.com
Address: 1670 Sierra Ave, Ste 303, Yuba City, CA 95993
Hours: Monday through Friday, 9:00am to 5:00pm
Disclosure: California’s last-resort fire program changes often, so details on this page may change. We work to keep it current. For the latest program information, talk to your Oakview broker or visit the California FAIR Plan at cfpnet.com, where current policyholders can also make payments and report claims. Oakview is an independent insurance broker. We represent you, the applicant or policyholder, and we are not an agent or representative of the California FAIR Plan. The program determines eligibility, policy issuance, and coverage terms.